Personal Finance Made Easy: Budget, Save, Invest, Pay Debt
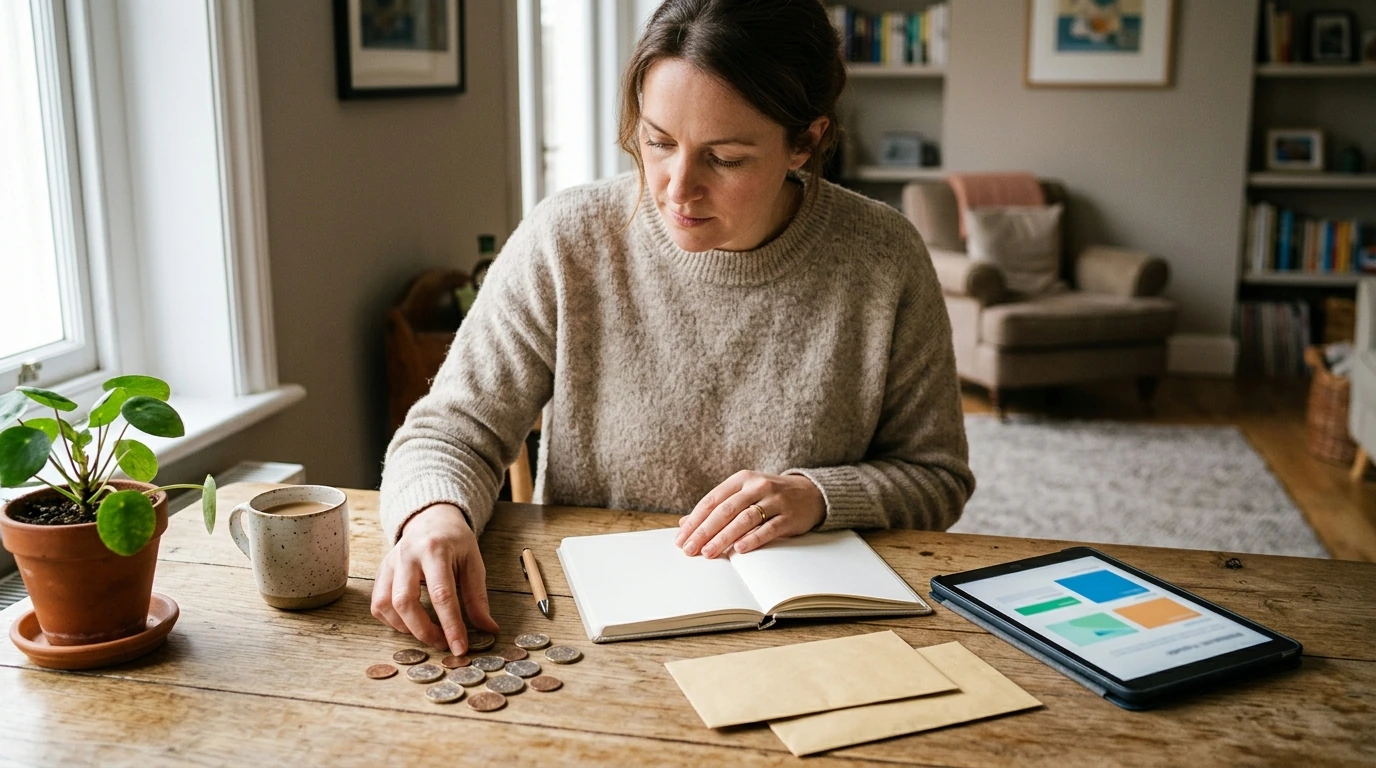
Personal Finance Made Easy: a simple plan you can actually follow
Money gets easier when there’s a clear job for every dollar—this week, next month, and years from now. Our team created Personal Finance Made Easy for real life: a flexible spending plan, saving that doesn’t rely on willpower, investing explained in plain language, and a debt payoff method you can stick with even when life gets busy.
Who this guide is for (and what it helps you stop doing)
- If you’re a beginner who wants one straightforward system instead of scattered tips.
- If you’re tired of paycheck-to-paycheck surprises and “where did it go?” spending.
- If your household is balancing multiple priorities (bills, kids, goals) and needs a repeatable routine.
- If you’re ready to move from minimum payments to a real debt plan.
- If you’re saving but want to start investing confidently—without jargon overload.
The goal isn’t perfection. It’s predictability: fewer money emergencies, fewer “oops” credit card swipes, and more progress you can see.
The 10-minute setup: know your numbers before you budget
Before you try to “budget,” capture a clean snapshot of what’s coming in and what has to go out. This is where calm comes from—clarity first, decisions second.
- List monthly take-home income (after taxes/benefits) and note any variable income separately.
- Write down fixed obligations (rent/mortgage, insurance, minimum debt payments, subscriptions).
- Estimate flexible spending (groceries, gas, childcare, dining, personal, fun).
- Identify “irregular” costs (car repairs, gifts, school fees, annual bills) and convert them to a monthly amount.
- Pick one weekly money date to review accounts and adjust—small check-ins prevent big mistakes.
Quick-start money map (fill this in once, then update monthly)
| Category | Monthly Target | Notes |
|---|---|---|
| Income (take-home) | $____ | Include steady income; track variable separately |
| Fixed bills | $____ | Housing, utilities, insurance, subscriptions |
| Flexible spending | $____ | Groceries, gas, eating out, personal spending |
| Irregular expenses (sinking funds) | $____ | Car, medical, school, gifts, annual renewals |
| Debt payoff (beyond minimums) | $____ | Choose snowball or avalanche amount |
| Saving & investing | $____ | Emergency fund, retirement, other goals |
Budgeting that doesn’t collapse mid-month
A budget breaks when it’s built on wishful thinking. We recommend a structure that prioritizes essentials, then progress, then lifestyle—so you can spend without sabotaging next week.
- Use a simple framework: cover essentials first, then savings/debt, then lifestyle spending.
- Build “guardrails,” not perfection: set spending caps for the categories that usually drift.
- Create a small buffer line (even $25–$50) to reduce overdrafts and last-minute credit use.
- Automate what matters most (bills, minimum payments, savings) so progress happens on busy weeks.
- Use a reset rule: if a category goes over, decide what gets reduced—no guilt, just rebalancing.
If you want extra structure, the Consumer Financial Protection Bureau has a helpful overview of budgeting basics: CFPB — Budgeting and money management.
Saving that sticks: emergency fund, sinking funds, and goal savings
Saving becomes realistic when you stop treating irregular expenses like “surprises.” That’s where sinking funds (mini-savings buckets) change everything.
- Start with a starter emergency fund for quick protection, then grow it over time.
- Separate “true emergencies” from expected-but-irregular expenses by using sinking funds.
- Name your savings goals (car replacement, moving, back-to-school, holiday spending) to reduce withdrawals.
- Make saving automatic: schedule transfers right after payday to avoid relying on willpower.
- If saving feels impossible, pause one expense temporarily and redirect that amount to a starter fund.
Debt management: pick a payoff method and make it predictable
Debt payoff works best when it’s a system, not a mood. Once you choose a method, your only job is to repeat it—month after month—until the balances are gone.
- List balances, interest rates, and minimum payments—clarity reduces stress.
- Choose a strategy: snowball (smallest balance first) or avalanche (highest interest first).
- Freeze new debt where possible: remove saved cards from shopping apps and reduce temptation triggers.
- Plan for setbacks: one “debt pause” month can be better than quitting entirely—restart next cycle.
- Track one scorecard metric monthly (total debt balance or total interest paid) to see progress.
Snowball vs. avalanche at a glance
| Method | Best for | How it works |
|---|---|---|
| Debt snowball | Motivation and quick wins | Pay extra toward the smallest balance first, keep paying minimums on the rest |
| Debt avalanche | Reducing interest cost over time | Pay extra toward the highest interest rate first, keep paying minimums on the rest |
Investing made understandable: the beginner-friendly path
Investing isn’t about predicting the market—it’s about consistent contributions over time, matched to your goals and time horizon. If you’re new, start simple and repeatable.
For clear, beginner-friendly definitions and examples, these are reliable starting points: Investor.gov — Investing basics and IRS — Retirement plans.
A weekly routine that turns your plan into progress
Recommended downloads from our store (pick what matches your next step)
- Personal Finance Made Easy Ebook – Budgeting, Saving, Investing & Debt Management Guide for Financial Freedom ($20.99): Use this as your “whole system” guide—start with the money map, then follow the chapters that match your current priority (stabilize, save, pay off debt, invest).
- Travel Security & Scam Awareness Guide | Digital Safety Handbook for Tourists, Solo Travelers & Business Trips ($10.99): Helpful if travel spending, card security, and scam prevention are part of protecting your budget.
- Cardio + Strength Done Right | How to Combine Cardio and Strength Training Effectively ($5.99): If you like checklists and routines, this pairs well with money habits—consistent schedules beat “when I feel like it.”
FAQ
What are the 5 basics of personal finance?
The five basics are managing cash flow with a budget, building savings (emergency and goals), managing debt with a payoff plan, investing for long-term goals, and protecting your finances through basics like insurance and fraud awareness. Our team built Personal Finance Made Easy around these pillars so you can set up one repeatable system.

Leave a comment