5 Personal Finance Basics: Budget, Save, Debt, Invest, Protect
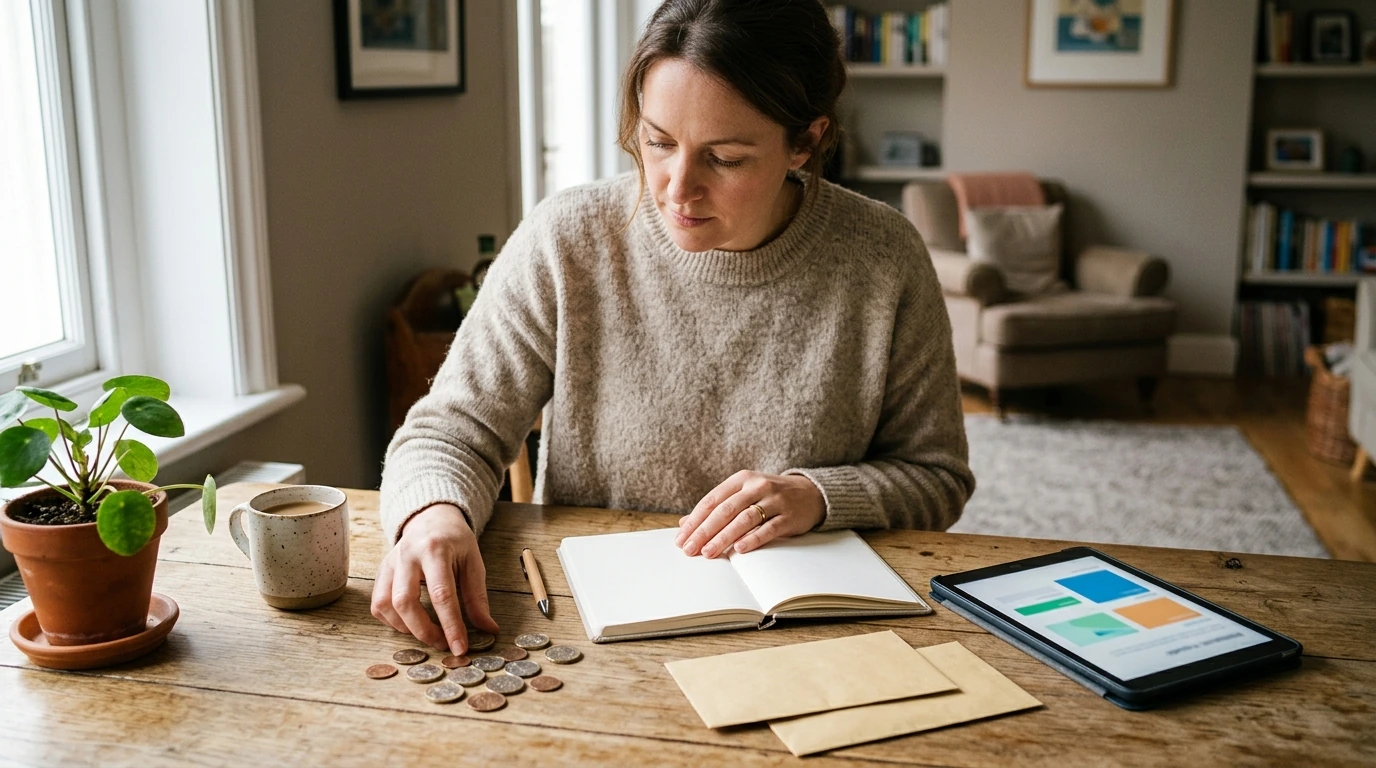
What are the 5 basics of personal finance?
Personal finance doesn’t have to be complicated to be effective. The five basics are simple building blocks you can return to during busy seasons—like pregnancy, postpartum, or any time your priorities and expenses shift. Our team uses these fundamentals to help you keep your money steady, reduce stress, and make room for the things your family truly needs.
1) Build a budget you can actually follow
A budget is your plan for what each dollar will do before it disappears on “miscellaneous.” Start with your fixed essentials (housing, utilities, insurance, childcare), then add flexible categories (groceries, fuel, personal spending). Give yourself a realistic buffer for the weeks that never go as planned.
2) Save consistently (even in small amounts)
Savings protects your day-to-day life from turning into a credit card emergency. Aim to start an emergency fund—first $500–$1,000, then work toward 3–6 months of core expenses. Automating even $10–$25 per paycheck builds momentum faster than waiting for a “perfect month.”
3) Manage debt with a clear payoff strategy
Debt isn’t just a balance—it’s a monthly payment that limits your choices. List debts by interest rate and minimum payment, then choose either the avalanche method (highest interest first) or snowball method (smallest balance first). Keep paying minimums on everything while you focus extra money on one target debt at a time.
4) Invest for long-term goals
Investing is how you turn time into growth, especially for retirement and future family needs. If you have access to an employer plan, start there and prioritize any match. Then consider IRA options and increase contributions gradually when income or expenses change.
5) Protect what you’re building
Protection includes the “boring” tools that prevent one unexpected event from derailing everything: health coverage, adequate auto/home or renters insurance, and a basic estate plan (beneficiaries, a will, guardianship choices). It’s also smart to review your coverage after major life changes.
For a step-by-step approach to budgeting, saving, investing, and paying down debt, visit our complete guide: Personal Finance Made Easy: Budget, Save, Invest & Pay Down Debt.
FAQ
What is a good emergency fund goal for a new parent?
A practical starting goal is $500–$1,000 for quick surprises, then build toward 3–6 months of essential expenses. If your income varies, aim closer to 6 months to create breathing room.

Leave a comment