Budgeting Like a Pro: Plan for Savings and Debt
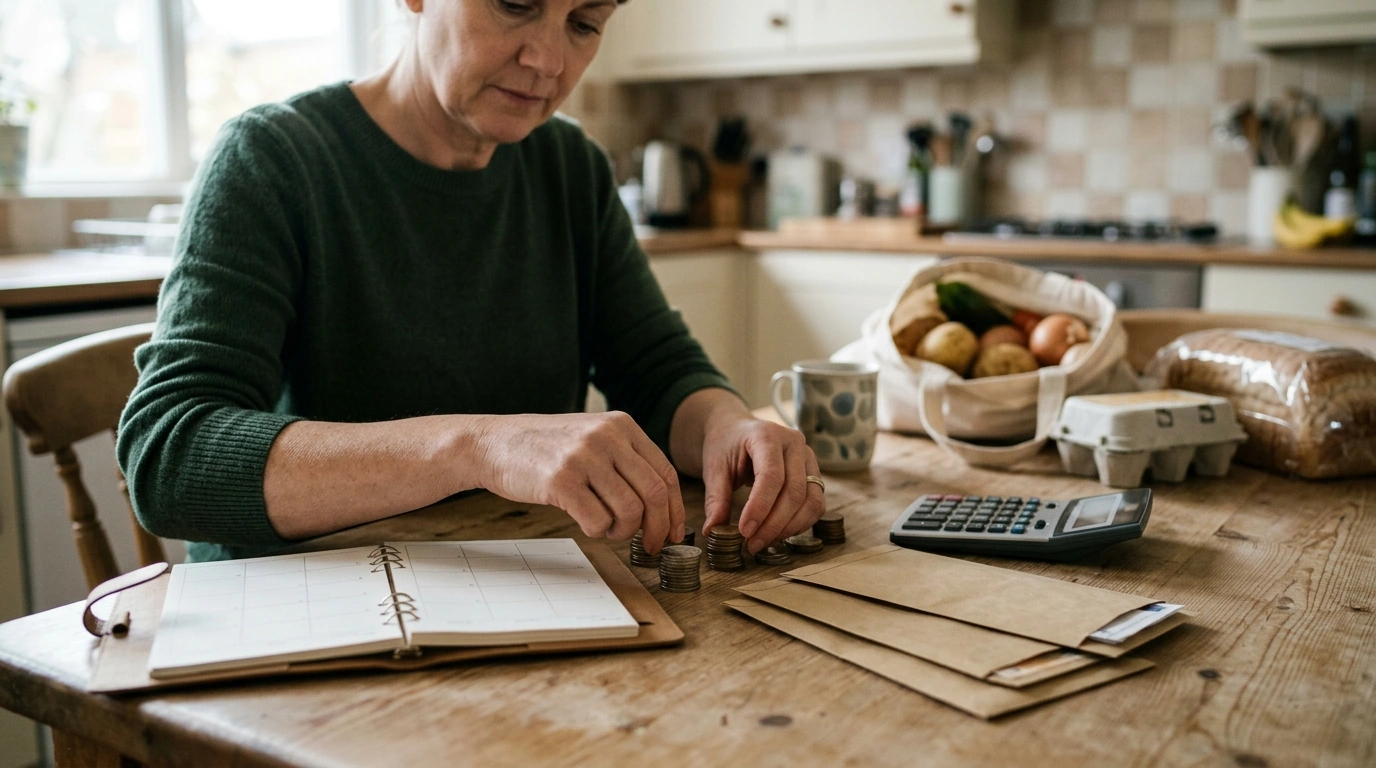
A budget can do more than tell you where last month’s money went. It can help you decide what matters before the next month begins, make room for savings, and give debt payments a clear place in your plan. You do not need a perfect system to start. You need a realistic picture of the money coming in, the costs going out, and one method you can keep using.
Start with the money coming in
Begin with your estimated monthly take-home income: the money available after taxes and other paycheck deductions. Add other dependable income you expect to receive. If your income changes from month to month, try building your first plan around a conservative amount rather than your best month. You can decide what to do with any additional income when it arrives.
Next, list recurring bills, such as housing, utilities, insurance, and minimum debt payments. Look back at recent transactions to estimate variable costs like groceries, gas, and dining out. Remember expenses that do not appear every month, too. Setting aside a little for an annual renewal or car maintenance can make those costs less disruptive when they come due.
Your first draft is a starting point, not a test. If a number turns out to be too low or too high, you can change it. The goal is to give yourself a useful plan, not to predict every purchase perfectly.
| Category | What to include | First step |
|---|---|---|
| Income | Take-home pay and other dependable income | Choose a planning amount |
| Essentials | Housing, groceries, utilities, and transportation | List expected costs |
| Flexible spending | Dining out, hobbies, and other choices | Set a realistic limit |
| Future goals | Savings and extra debt payments | Give each goal an amount |
Choose a budgeting method you can maintain
Three familiar approaches offer different ways to make decisions. With zero-based budgeting, you assign every dollar of planned income a purpose. That purpose can be a bill, groceries, savings, debt payoff, or a buffer. It does not mean you must spend every dollar or empty your bank account.
The 50/30/20 guideline groups your money into needs, wants, and savings or debt goals. It can give you a quick view of your priorities, but the percentages are a starting point, not a rule. Your essential costs and income may call for a different split. Pay-yourself-first puts money toward a priority goal before flexible spending begins, often through a transfer after payday. The transfer still needs to leave enough for bills and everyday needs.
Choose based on the decision you need help making. If you want close control, try assigning amounts category by category. If you need a broad overview, group your spending first. If saving consistently is the sticking point, start with an affordable transfer. You can also combine ideas—for example, plan by category while moving a set amount to savings on payday.
| Method | Useful when | Try this first |
|---|---|---|
| Zero-based budgeting | You want to account for all planned income | Assign amounts to bills, spending, savings, and debt |
| 50/30/20 guideline | You want a broad view of your priorities | Sort expenses into needs, wants, and goals |
| Pay-yourself-first | You want to save more consistently | Choose an affordable transfer after payday |
Make debt payoff and savings part of the same plan
Put required debt payments in your budget alongside your other obligations. Then consider an amount you can move into accessible savings without making ordinary expenses harder to cover. If money remains after those priorities and your planned spending, you may choose to direct an extra payment toward one debt.
The right balance depends on your interest rates, payment obligations, and need for cash you can reach quickly. A small emergency cushion, for instance, may help you handle an unexpected cost without relying on more debt. You can also name a savings goal for a known expense, such as a renewal or a repair, and set aside money for it over several months.
Keep the amounts repeatable. A modest contribution you can make regularly may serve you better than an ambitious target that leaves no room for groceries or transportation. For more guidance on putting income and expenses together, our team recommends the Consumer Financial Protection Bureau’s budgeting resources and Consumer.gov’s guide to making a budget.
Put the plan to work this month
Draft your budget before the month starts, or before your next paycheck if that timing is easier. Give upcoming bills a place first, then plan for variable expenses, savings, and any extra debt payment. Once a week, compare your transactions with your plan. A short check-in can show you whether a category needs attention while there is still time to adjust.
If you want to explore these approaches together with debt payoff and savings planning, our Budgeting Like a Pro: Complete eBook brings those topics into one resource. Whatever method you choose, remember to give optional purchases a place in the plan, too. Even a specific interest, such as our New Puppy Training Starter Guide, belongs in flexible spending rather than being treated as an unexpected bill.
FAQ
Does zero-based budgeting mean having nothing left in my bank account?
No. It means giving all your planned income a purpose; money assigned to savings or a buffer still has a job.
Do I have to follow 50/30/20 percentages exactly?
No. Treat the percentages as a starting guideline and adjust them for your income, essential costs, and goals.
Should I save money while paying off debt?
Many budgets can include both required debt payments and some accessible savings. The balance depends on your payment obligations, interest rates, and need for cash.

Leave a comment